

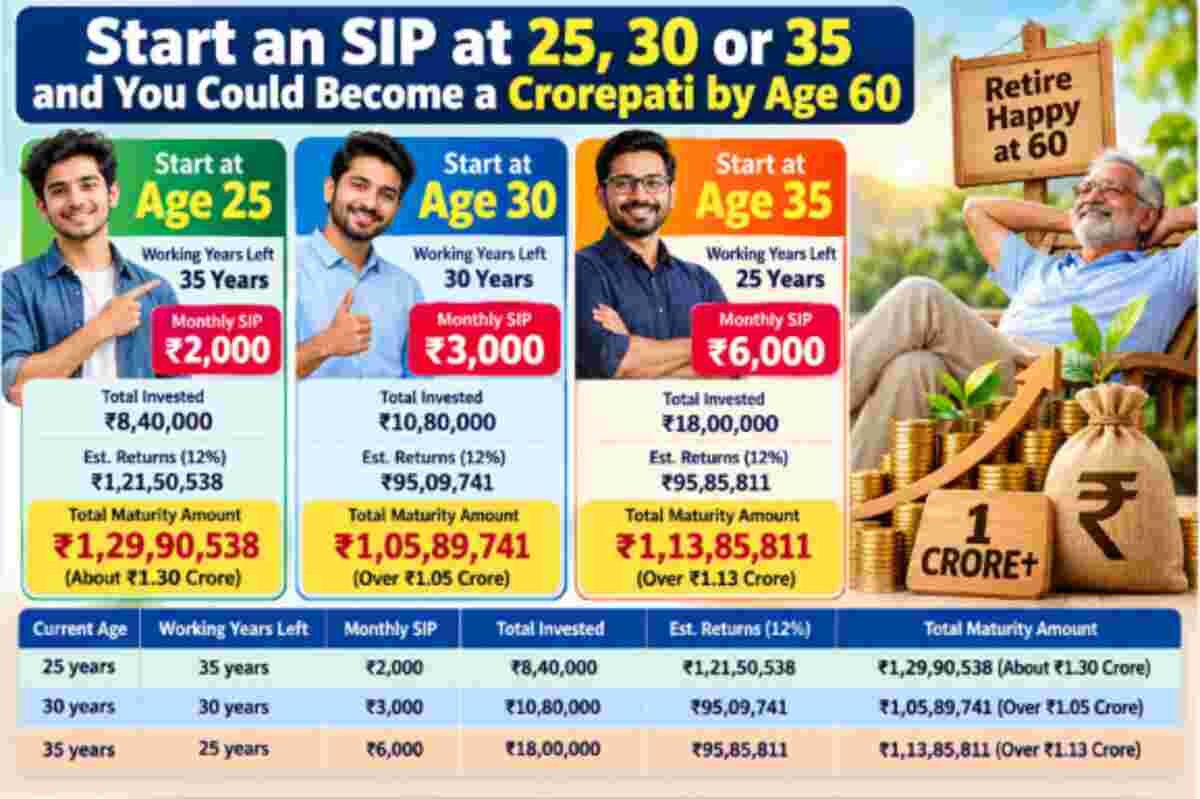
Starting a retirement SIP according to your age can put a ₹1 crore-plus fund within reach by 60. Assuming an estimated 12% annual return, a ₹2,000 monthly SIP from age 25 could grow to about ₹1.30 crore, ₹3,000 from age 30 to over ₹1.05 crore, and ₹6,000 from age 35 to over ₹1.13 crore. SIPs are market-linked, so returns are not guaranteed.
Why Retirement Planning Matters
When regular income stops in old age, the money you have saved is what you fall back on. That is why retirement planning is considered one of the most important financial tasks today.
If you have not started yet, now is the time. First work out how many working years you have left, then begin a monthly SIP that matches that timeline.
How to Calculate Your Remaining Working Years
Retirement age for salaried people is generally taken as 60. Subtract your current age from 60 to see how long you have to build your retirement fund.
- At age 25: 35 working years left (60 − 25).
- At age 30: 30 working years left (60 − 30).
- At age 35: 25 working years left (60 − 35).
How Much SIP to Invest Based on Your Age
The calculations below assume an estimated 12% annual return (CAGR). This is an assumption, not a guaranteed return.
Age 25: 35 Years Left, ₹2,000 Monthly SIP
Starting young means even a small ₹2,000 monthly SIP can build a large fund. Over 35 years, you would invest ₹8,40,000 from your own pocket.
Estimated returns of about ₹1,21,50,538 would take the total maturity amount at 60 to ₹1,29,90,538, or roughly ₹1.30 crore.
Age 30: 30 Years Left, ₹3,000 Monthly SIP
Those starting at 30 should run an SIP of at least ₹3,000 per month. Total investment over 30 years would be ₹10,80,000.
Estimated returns of ₹95,09,741 would lift the fund at 60 to ₹1,05,89,741, which is over ₹1.05 crore.
Age 35: 25 Years Left, ₹6,000 Monthly SIP
Those who begin at 35 need to invest at least ₹6,000 a month to reach crorepati status. Total investment over 25 years would be ₹18,00,000.
Adding estimated returns of ₹95,85,811 would bring the fund at 60 to ₹1,13,85,811, which is over ₹1.13 crore.
At a Glance: Age-Wise SIP Math
| Current Age | Working Years Left | Monthly SIP | Total Invested | Est. Returns (12%) | Total Maturity Amount |
| 25 years | 35 years | ₹2,000 | ₹8,40,000 | ₹1,21,50,538 | ₹1,29,90,538 (about ₹1.30 crore) |
| 30 years | 30 years | ₹3,000 | ₹10,80,000 | ₹95,09,741 | ₹1,05,89,741 (over ₹1.05 crore) |
| 35 years | 25 years | ₹6,000 | ₹18,00,000 | ₹95,85,811 | ₹1,13,85,811 (over ₹1.13 crore) |
Where Does SIP Money Go?
A SIP invests your money in mutual funds. Because it is linked to the market, it carries risk and returns cannot be guaranteed.
Even so, SIPs are generally considered less risky than investing directly in the stock market. The average return is taken as 12%, which is described as better than many government schemes.
Compounding makes money grow faster over time, which is why long-term SIPs are seen as a good way to build wealth.
Conclusion: Starting Early Is the Biggest Advantage
A long-term SIP is an effective route to wealth creation. It does carry market risk, but the power of compounding and an estimated 12% average return make it more attractive than traditional options.
The numbers show that starting early lets a smaller monthly amount grow into a large fund. Begin investing as per your capacity, and consider speaking to a certified financial advisor before you invest.

